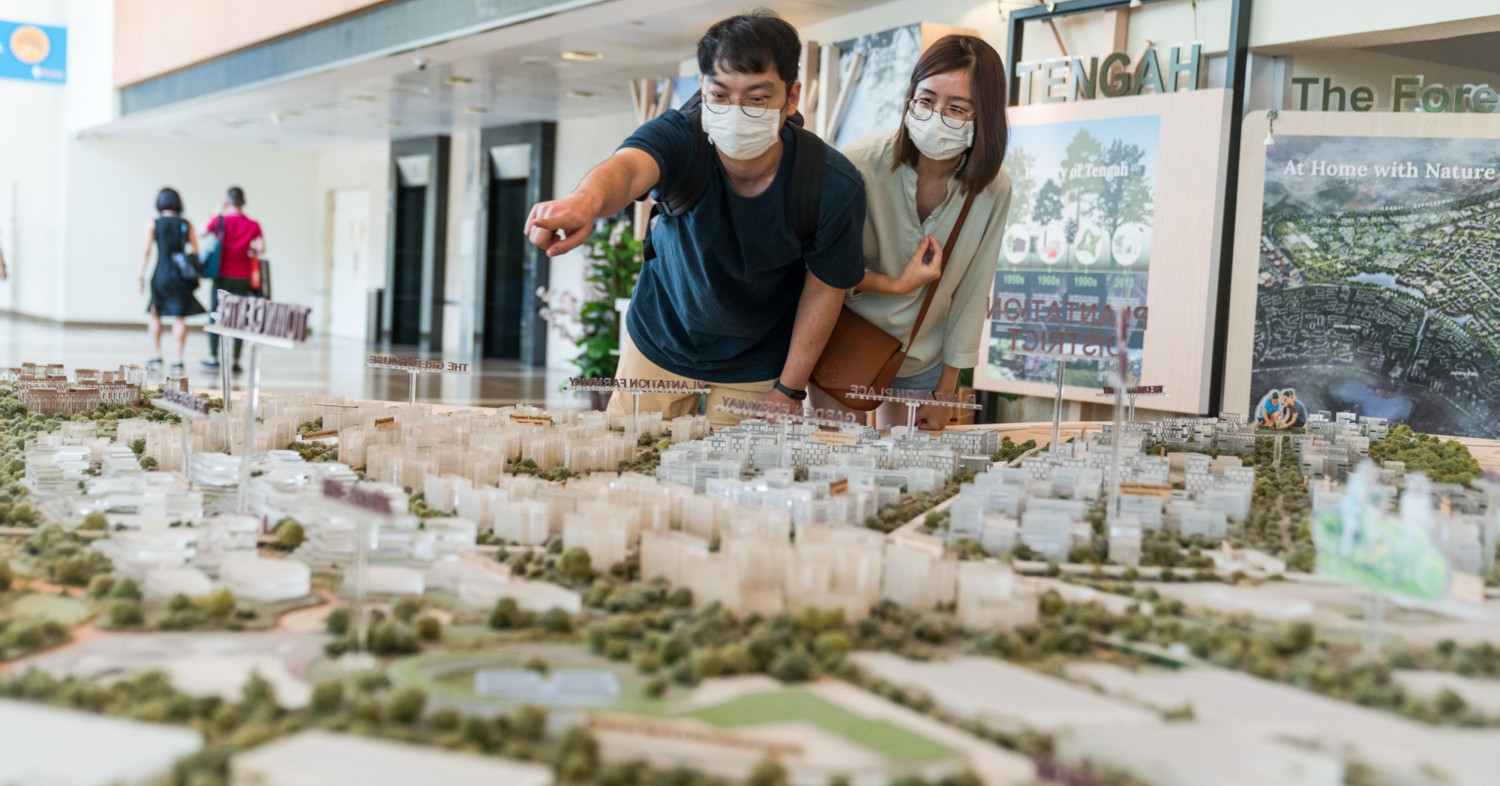
At 8.45pm on a weeknight, Wei Lin — 27, working in marketing, saving for her first home — does what her parents would never have dreamed of doing at her age: she cross-checks the transaction history of a Tampines 4-room flat against every comparable resale within a two-kilometre radius, on her phone, in bed.
Two days later, she walks into a viewing already knowing the flat's price per square foot, its remaining lease, what the seller paid in 2019, how long the unit has been sitting on the market, and what a similar flat two blocks away fetched last month. The agent barely gets through his introduction before her first question: "Why is this asking price 6% above the most recent comparable sale?"
Wei Lin doesn't think of herself as a property expert. She's a digital-first homebuyer — part of the first generation of Singaporeans for whom the property market is not a guarded black box, but a dataset. And that single cultural shift is quietly rewiring how resale flats are researched, priced, negotiated and sold across the island.
This article looks at how property analytics has turned Gen Z buyers into sharper researchers, why the resale market has become their natural hunting ground, and what this means for everyone else in the transaction — including the agents on the other side of the table.
The First Generation That Shops for Homes Like It Shops for Everything Else
Gen Z — broadly defined as those born between 1997 and 2012 — is only now entering the property market in force. The oldest members are around 28, which is precisely the age when Singaporeans start thinking seriously about marriage and a first home. The median age at first marriage in Singapore hovers around 30 for men and 29 for women, according to government statistics. In other words: Gen Z is standing at the doorstep of its biggest financial decision ever, armed with habits formed in the era of instant everything.
They comparison-shop for $6 bubble tea. They read three reviews before buying a $25 T-shirt. They do not know a world without Google Maps street view, online banking, or the ability to see, in real time, how much someone else paid for almost anything. So when it comes to a $500,000 flat — the single largest purchase most of them will ever make — the idea of relying on a single agent's say-so feels, to them, almost reckless.
This is a profound departure from how their parents bought homes. The previous generation grew up in a world where property information was expensive and scarce. The agent's booklet of listings was the primary source of truth. "Price trends" were anecdotal — the colleague whose cousin sold high, the uncle who knew a guy in the district office. The weekend routine was a series of viewings with no prior data, where the agent's framing was the only frame you got.
That gatekeeping model has collapsed. Today, every HDB resale transaction is public record. URA publishes private property caveats. The government's master plans and MRT line announcements are online. And a wave of platforms — Hiva included — has turned this raw data into something readable: per-project prices, district scores, and market trends that a 25-year-old can scan during a lunch break.
Here's roughly what a digital-first buyer does before the first viewing:
- Pulls up every past transaction for the project in question
- Benchmarks the flat's price per square foot against neighbouring projects
- Checks the remaining lease and what it means for financing
- Runs grant and affordability calculators with their actual CPF balances
- Reads up on planned MRT lines, malls and schools nearby
- Cross-checks the agent's asking price against the data trail
None of this requires insider access. It requires the willingness to look. And that is the defining trait of the generation that grew up looking.
Why the Resale Market Became Gen Z's Hunting Ground
For most of the 2010s, the standard advice to young couples was simple: ballot for a Build-To-Order (BTO) flat and wait. The BTO route offered subsidised pricing, a fresh 99-year lease, and a predictable path to ownership. But the pandemic-era construction crunch changed the calculus. Waiting times stretched, with many projects launched between 2021 and 2023 taking more than four years to complete — the longest waits in over a decade.
For a couple in their late 20s, four years is not an abstract number. It's the difference between starting a family in their early 30s or mid-30s. It's four more years of renting — and Singapore rents spiked sharply in 2022 and 2023. It's four years of watching resale prices climb and wondering if the BTO discount is really a discount once you factor in time.
HDB has since committed to bringing waiting times back to three to four years for projects launched from 2025. But the resale market's appeal is no longer just about speed. Consider the price trajectory. According to HDB's Resale Price Index, resale prices have climbed steeply since the pandemic:
HDB Resale Price Growth by Year (%)
The chart above, based on HDB's official index, shows the 2021 surge of 12.7%, the 2022 follow-through of 10.3%, a cooler 2023 at 4.9%, and a fresh acceleration to 8.7% in 2024 — a record-high level for the index. For a generation that came of age during the 2016-2019 property doldrums, the message is unmistakable: resale flats are no longer the "settled" option. They are assets that have demonstrated real growth.
Now add the policy layer. First-timer families buying a resale flat can stack a series of subsidies:
- CPF Housing Grant (resale): up to $50,000 for a 4-room flat or larger (up to $40,000 for smaller flats)
- Enhanced CPF Housing Grant: income-tiered, up to $80,000
- Proximity Housing Grant: up to $30,000 if you live with or near your parents
Combined, a lower-income first-timer family buying a 4-room flat near their parents can be looking at a six-figure subsidy package — a sum large enough to cover a meaningful chunk of the down payment. On top of that, buying an HDB resale flat as a first property attracts no Additional Buyer's Stamp Duty (ABSD), unlike the private market, where foreigners now face a 60% ABSD rate introduced in 2023.
And the market itself is liquid. Roughly 28,000 to 30,000 resale flats have changed hands each year in recent years, according to HDB transaction data — a deep pool that young buyers can actually enter without ballot luck. The pie chart below shows the rough composition of that market by flat type:
HDB Resale Transactions by Flat Type (approximate share)
The 4-room flat is the workhorse of the resale market, and it's also the segment most young couples gravitate toward — big enough for a family, small enough to be within reach. The data says the market is actively trading the exact product Gen Z wants to buy.
Then there's the psychology. The explosion of million-dollar HDB transactions has rewritten what young buyers believe resale flats are capable of. According to industry year-end reviews, the number of HDB resale flats sold for at least $1 million has grown from just 57 in 2019 to an estimated 259 in 2021, 369 in 2022, around 460 in 2023, and reportedly more than 500 in 2024:
Million-Dollar HDB Resale Transactions (approximate count)
The point isn't that every flat will become a million-dollar flat. The point is that a generation raised on data has watched HDB resale prices do something their parents' generation never imagined — and they want in on the analysis.
How Gen Z Reads a Resale Flat Through a Property Analytics Lens
The most important mental shift the digital-first buyer makes is moving from town-level thinking to project-level thinking.
Ask a traditional agent "how much is a 4-room flat in Bishan?" and you'll get a range — perhaps "around $700,000 to $800,000." That's not wrong, but it's almost useless. Within the same town, two 4-room flats ten minutes' walk apart can transact at very different price-per-square-foot (PSF) levels, because one is in a 1990s project with a dated layout and lower floor, while the other is in a newer development with better finishing and a quieter internal-facing stack.
The analytics lens disaggregates the market until the comparison is meaningful. Instead of asking "What's a Bishan 4-room going for?", the digital-first buyer asks: "What did this exact project transact at in the last six months, and how does this specific unit's asking price compare?"
Here is the core checklist a Gen Z buyer typically runs before shortlisting:
| Check | Why it matters | Where to look |
|---|---|---|
| Price per square foot | Normalises comparison across different flat sizes | HDB transaction records / analytics platforms |
| Same-project recent transactions | Establishes the fair value anchor for that specific block | HDB transaction data |
| Remaining lease | Affects loan tenure, CPF usage and future buyer pool | HDB records |
| Future supply nearby | New BTO launches can dilute resale demand in the area | URA / HDB master plan data |
| Upcoming amenities | New MRT lines and malls historically re-rate nearby flats | LTA / URA announcements |
| Asking price vs valuation gap | Reveals whether a listing is priced ambitiously or attractively | Platforms / agent valuation reports |
This is where platforms like Hiva slot in. They take the same public data anyone can access and organise it into something a busy 27-year-old can act on quickly: per-project price analytics, district-level scoring, and market trend indicators. The district scores draw on structural factors — connectivity to MRT and LRT stations, proximity to hawker centres, malls and schools, planned supply in the pipeline, and historical price momentum — and the methodology is validated out-of-sample, meaning the scores aren't tuned to retroactively fit past prices. What buyers see is a distilled, comparable view of whether an area is priced richly or reasonably relative to what it offers.
The workflow looks something like this:
graph LR
A["Filter towns, budget, grants"] --> B["Compare per-project pricing"]
B --> C["Shortlist 10-15 flats"]
C --> D["Screen by PSF, lease, scores"]
D --> E["Visit the shortlisted units"]
E --> F["Check valuation & financing"]
F --> G["Negotiate with the data"]
G --> H["Buy or walk away"]
Notice what's missing from that flow: "ask the agent what the market price is." The agent enters the process later — at the visit and negotiation stage — rather than at the discovery stage. That's a subtle but significant power shift.
The digital-first buyer also reads soft signals that used to be invisible: how long a listing has been on the market, whether the seller has cut the asking price, how the asking price relates to the latest HDB valuation, and how quickly the same project is turning over. A flat that has been listed for 90 days with two price cuts tells a very different story from one that moved in a week.
The Undervalued Flat Playbook: Spotting a Gem Before the Crowd Does
Call it what you will — "hidden gems," "undervalued resale flats," "value plays" — the hunt for a flat that trades below what its fundamentals imply is the most exciting game in the Singapore property market. And it is precisely the game Gen Z is best equipped to play, because spotting an undervalued flat is not about luck. It's about pattern recognition — and patterns live in data.
Here are the patterns that keep showing up in the data:
1. The infrastructure bet. Flats near a planned MRT line or a new mall tend to re-rate when the amenity actually opens. Buyers who identify the announcement early and buy before construction completes are effectively pricing in an upgrade the wider market hasn't fully digested yet. This is a well-documented phenomenon in Singapore — property research firms have repeatedly shown that proximity to new MRT stations and major commercial developments is correlated with stronger resale price growth.
2. The overlooked town dynamic. Two towns can have nearly identical commute times to the CBD and comparable amenities, yet trade at noticeably different PSF levels. Sometimes the gap is explained by prestige — family name, nostalgia, a "better" address. Sometimes it's simply momentum: a town that was hot last cycle stays hot because everyone anchors on recent transaction highs. The digital-first buyer looks for the town where the fundamentals (connectivity, amenities, demographics) are similar but the prices haven't caught up.
3. The flat-type skew. Executive flats in mature estates sometimes trade at a lower PSF than 5-room flats nearby, simply because they're big (typically over 1,200 sq ft) and the pool of buyers who can afford a million-dollar HDB is smaller. For a buyer willing to be patient, that PSF discount can be a genuine value play — provided you accept that the exit pool will be smaller too.
4. The "old but well-kept" corner. Flats with 50-60 years of lease remaining trade at meaningful discounts to identical layouts with full lease. The discount exists for a reason: financing tightens as the lease shortens. Both CPF and loan rules restrict how much you can borrow against a short lease, which shrinks the future buyer pool. But for a young couple planning to stay 10-15 years and then sell, a shorter-lease flat in a great location can be the cheapest way to live in an area that would otherwise be out of reach.
The playbook, however, comes with a critical warning: the cheapest flat is not automatically a gem. In the same project, the low-PSF outlier might be on a low floor facing a rubbish chute, or suffer from west-sun heat, or sit directly above the bin centre. The data will tell you that the flat is cheap. It takes a site visit and some street sense to know why.
The smart approach is to use analytics as the filter, not the verdict. Screen out the overpriced listings with data; then use your own eyes to eliminate the cheap ones with fatal flaws. What remains — the flat priced below its project's recent range but without the obvious downsides — is your shortlist of genuine candidates.
BTO vs Resale: The Decision Tree Gen Z Buyers Actually Run
No discussion of the digital-first homebuyer is complete without the question that dominates every young couple's dinner-table conversation: BTO or resale?
The conventional wisdom used to be automatic: BTO, because it's cheaper. And it's true that BTO flats are priced at a significant discount to comparable resale flats — HDB has indicated that discount is in the region of 20%. But the digital-first buyer doesn't treat that 20% as the whole story. They model the full comparison: price, timing, grants, rental costs during the wait, opportunity cost, and the risk that prices move while you wait.
graph TD
A["Ready for first home?"] --> B{"Can you wait 3-4 years?"}
B -->|"No"| C["Resale route"]
B -->|"Yes"| D{"Want the lowest upfront price?"}
D -->|"Yes"| E["BTO route"]
D -->|"No"| C
C --> F{"Grants, loan and move-in plan OK?"}
F -->|"Yes"| G["Buy resale now"]
F -->|"No"| E
The comparison table below captures how a data-literate buyer frames the two paths:
| Factor | BTO | Resale |
|---|---|---|
| Price | Around 20% below comparable resale | Market price; negotiable with the right data |
| Timeline | 3-4 years (longer at the recent peak) | Move in within 1-3 months |
| Subsidy | Discount baked into the price | Explicit grants, stackable up to six figures |
| Lease | Fresh 99 years | Depends on flat age; shorter leases restrict financing |
| Flexibility | Locked into the project and wait | Choose exact location, flat, and timing |
| Ballot risk | Real — oversubscription is common | Certainty of outcome |
Here's an illustrative sketch of how the thinking runs. Suppose a couple earning $8,000 a month compares a 4-room BTO at around $450,000 with a comparable resale at $580,000 in the same region. The BTO saves roughly $130,000 in price — but it costs a 3-4 year wait, during which they're likely renting at $3,000 a month or more, which adds up to over $100,000 in rent. The resale buyer, meanwhile, gets grants of maybe $50,000 to $60,000 at their income level, moves in immediately, and starts building equity in a market that has been appreciating at high single digits annually. The "obvious" BTO advantage evaporates under scrutiny — or doesn't, depending on when you run the numbers and what prices do next.
That's the whole point. The right answer changes month to month, which is exactly why this generation treats property decisions as ongoing analyses rather than one-time leaps of faith.
There's one more constraint the analytics-minded buyer never forgets: the Minimum Occupation Period (MOP). A resale HDB flat still carries a 5-year MOP before you can sell it or upgrade to a private property. The flat you buy at 28 is your home and your asset for at least the next five years — so the neighbourhood, the commute, and the long-term lease math matter far more than the short-term price spike.
What Property Agents Can Learn From the Digital-First Homebuyer
Here's the honest tension in the market right now. Singapore has around 31,000 registered property agents and salespersons, according to CEA statistics — a large, competitive profession built on a model that assumed information asymmetry. And that asymmetry is gone.
In the old model, the agent's value was partly access: they knew what was on the market, what things "should" cost, and how to navigate the paperwork. Today, a 26-year-old with a phone knows what things should cost — often more accurately than the agent does, because they've studied the same project's transaction history for three weeks straight.
But the data hasn't made agents obsolete. It has redefined the job. The most successful agents in the resale market are no longer information gatekeepers; they're interpreters, negotiators and process managers:
flowchart LR
A["Old role: information gatekeeper"] --> B["New role: advisor & negotiator"]
B --> C["Verify and interpret data"]
B --> D["Manage process and paperwork"]
B --> E["Negotiate price and terms"]
B --> F["Off-market access"]
Young buyers still want agents. They just want them for different things:
| Old expectation | New expectation |
|---|---|
| "Tell me what the market price is" | "Interpret the data I've already seen" |
| "Find me listings" | "Access off-market units and verify listings" |
| "Explain the process" | "Manage the process end-to-end, from Option to Purchase to key collection" |
| "Give me peace of mind" | "Add analytical rigour to my decision" |
The agents who thrive in this environment are the ones who lean into the data instead of fighting it. A listing agent whose pitch to a seller is "your asking price is 4% above the most recent comparable in your block, and here's the chart to prove it" is far more persuasive — and far more credible — than one who argues from gut feel. A buyer's agent who shows up to a negotiation with transaction history, valuation gaps, and time-on-market data wins the seller's respect and often the deal.
The flip side is harsh: agents who still operate with photocopied listings and generic "market trends" can expect to be ghosted. Gen Z buyers don't just compare flats — they compare agents. And they have an app for that too.
Food for Thought
A few questions worth chewing on, whether you're buying soon or just watching the market evolve:
-
Town averages vs project reality — If two flats ten minutes apart in the same town can trade at very different price-per-square-foot levels, how much do "District 19 median prices" really tell you? Where does an aggregate figure mislead, and where is it genuinely useful?
-
The cheap outlier — When you spot a flat trading well below its project's recent range, what's your first hypothesis: hidden flaw, motivated seller, or market inefficiency? What specific data would you pull to test that hypothesis before viewing?
-
The BTO trade-off — Would you accept a 20% lower price on a BTO in exchange for a 3-4 year wait, or pay up for a resale you can move into next quarter? How would you calculate the break-even point, and what assumptions (rent, price growth, interest rates) would dominate your answer?
-
Trust but verify — Twenty years ago, the agent's price opinion was the standard. Today, what three data points would you check before accepting any agent's pricing claim? Would you ever rely on a single source?
-
The future of advice — As AI tools make property analytics instant and comprehensive, what will human advice be worth? If the data is free and the analysis is automated, would you still pay a professional — and for what exactly?
The Data-Disciplined Generation
Every generation believes it is smarter with money than the last. For Gen Z, that belief has a technological foundation. They are the first homebuyers in Singapore history to enter the market with the full transaction record in their pocket — not just the ability to find data, but the expectation that they should.
That changes the resale market in a fundamental way. When both sides of a negotiation are looking at the same price history, the conversation shifts from "trust me" to "show me." Sellers price more carefully because buyers can verify. Agents add value by interpretation, not withholding. And the flats that are genuinely undervalued — the resale gems — get found faster, by whoever reads the data most carefully.
That's not a small thing. In a market as mature and policy-driven as Singapore's, every edge counts. And the edge is no longer in having a "source" — it's in having a framework.